Introduction
A personal loan can be a useful financial tool when you need extra money to manage important expenses, achieve personal goals, or handle unexpected situations. Unlike some other types of loans, personal loans can generally be used for a variety of purposes, depending on the lender’s terms and conditions.
However, taking out a personal loan is a financial responsibility that requires careful planning. Borrowing money without a clear repayment strategy can create unnecessary financial pressure. The key is to use the funds wisely, focus on essential needs, and make sure the monthly payments fit comfortably within your budget.
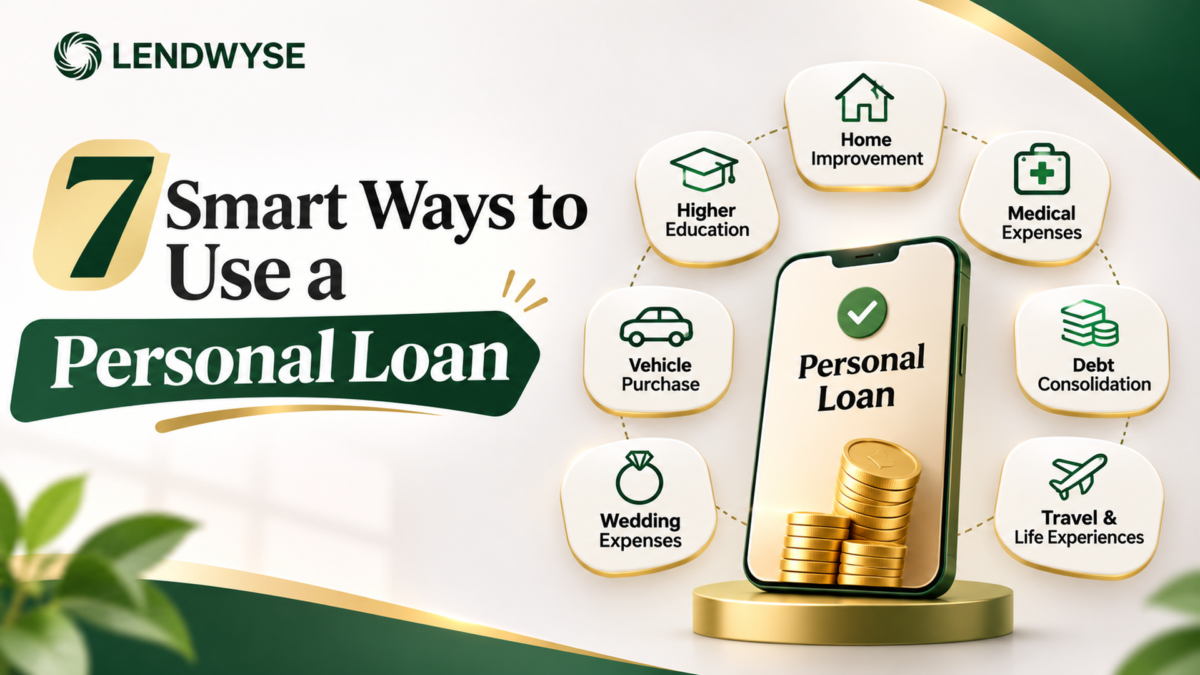
In this article, we will explore seven smart ways to use a personal loan and explain how responsible borrowing can help you manage your finances more effectively.
1. Consolidating High-Interest Debt
One of the smartest ways to use a personal loan is to consolidate multiple high-interest debts into a single payment.
If you have outstanding credit card balances, payday loans, or other expensive debts, managing several monthly payments can become stressful. A personal loan may allow you to combine eligible debts into one loan with a fixed repayment schedule.
Benefits of Debt Consolidation:
- Simplifies monthly financial management.
- May reduce the overall interest rate.
- Provides a predictable repayment schedule.
- Helps you focus on paying down existing debt.
Before consolidating your debts, compare the personal loan’s interest rate, origination fees, repayment period, and total borrowing cost. Debt consolidation is only beneficial when the new loan offers a genuine financial advantage.
2. Covering Unexpected Medical Expenses
Medical emergencies can happen without warning and may require immediate financial attention. Hospital visits, diagnostic tests, dental procedures, and other healthcare expenses can place unexpected pressure on your budget.
A personal loan may help cover necessary medical expenses when savings or other affordable payment options are insufficient.
Why It Can Be Helpful:
- Provides access to funds for urgent healthcare needs.
- Helps manage large medical bills through installments.
- Can reduce the need to use high-interest credit cards.
- Offers a structured repayment plan.
Before applying, check whether your healthcare provider offers installment plans, insurance coverage, or financial assistance. Borrow only what you genuinely need and can comfortably repay.
3. Making Essential Home Improvements
Your home is one of your most valuable assets, and maintaining it is an important financial responsibility. Sometimes, necessary repairs or improvements require more money than you currently have available.
A personal loan can help finance essential home improvement projects, such as:
- Repairing damaged roofs or plumbing systems.
- Upgrading electrical installations.
- Replacing old windows and doors.
- Improving kitchen functionality.
- Installing energy-efficient appliances.
- Addressing structural or safety issues.
Well-planned home improvements can improve comfort, safety, and potentially increase property value.
However, avoid borrowing excessively for purely decorative upgrades. Focus on projects that provide practical benefits and fit within your financial limits.
4. Investing in Education and Professional Development
Education and professional development can create valuable opportunities for long-term career growth. However, tuition fees, certification programs, professional training, and educational materials can be expensive.
A personal loan may help finance certain educational expenses when more suitable funding options are unavailable.
Potential Uses Include:
- Paying for professional certification courses.
- Enrolling in career development programs.
- Purchasing essential learning equipment.
- Attending specialized training workshops.
- Funding skill-based educational programs.
Before borrowing, evaluate the potential return on your investment. Consider whether the course or qualification can realistically improve your employment opportunities or earning potential.
Also compare personal loans with scholarships, grants, employer-sponsored education, and dedicated student financing options.
5. Managing Major Life Events
Important life events often come with significant expenses. Weddings, family celebrations, relocation, and other major milestones may require careful financial preparation.
A personal loan can provide additional financial flexibility when planned expenses exceed available savings.
For example, borrowed funds may help cover:
- Wedding-related expenses.
- Moving and relocation costs.
- Essential travel expenses.
- Important family arrangements.
- Other necessary personal commitments.
Although personal loans can make these expenses easier to manage, it is important to distinguish between essential costs and unnecessary spending.
Create a realistic budget before borrowing and avoid taking on long-term debt for expenses that could be reduced or postponed.
6. Purchasing Essential Equipment or Appliances
Certain purchases are necessary for everyday life, work, or household management. When an essential appliance or piece of equipment breaks down unexpectedly, replacing it immediately may be financially challenging.
A personal loan may help cover the cost of important purchases, including:
- Refrigerators and washing machines.
- Computers and laptops for professional use.
- Essential household equipment.
- Work-related tools and devices.
- Other necessary technology.
Before financing a purchase, compare the total cost of a personal loan with retailer installment plans and other available payment options.
It is also important to consider whether the item is genuinely necessary and whether its expected useful life justifies the borrowing cost.
7. Building Financial Stability During Temporary Income Gaps
Unexpected income disruptions can make it difficult to manage regular household expenses. Temporary unemployment, delayed payments, or a short-term business slowdown may affect your ability to pay essential bills.
A personal loan may provide temporary financial support in certain situations, provided you have a realistic plan for repayment.
Potential essential expenses include:
- Rent or housing payments.
- Utility bills.
- Groceries and household necessities.
- Transportation expenses.
- Other unavoidable financial obligations.
However, borrowing to cover recurring expenses can become risky if your income does not recover. A personal loan should not be treated as a permanent solution to ongoing financial difficulties.
Whenever possible, explore emergency assistance, payment arrangements, temporary income opportunities, and expense reductions before taking on additional debt.
Important Factors to Consider Before Taking a Personal Loan
Although personal loans offer flexibility, responsible borrowing is essential. Before submitting an application, consider the following factors:
1. Compare Interest Rates
Different lenders offer different interest rates depending on their lending policies, loan amounts, repayment periods, and borrower eligibility. Compare multiple offers to find a competitive rate.
2. Understand the Total Loan Cost
Do not focus only on the monthly installment. Review the complete repayment amount, including interest, processing fees, origination charges, and applicable penalties.
3. Choose an Affordable Repayment Period
A longer repayment period may reduce your monthly installment but can increase the total interest paid. Select a repayment term that balances affordability with overall borrowing costs.
4. Review Your Financial Situation
Calculate your monthly income, essential expenses, existing debts, and available savings. Make sure you can afford the new installment without compromising your basic financial needs.
5. Read the Loan Agreement Carefully
Understand all terms and conditions before accepting an offer. Pay attention to late payment fees, early repayment charges, variable interest rates, and other contractual obligations.
6. Borrow Only What You Need
Avoid borrowing more than necessary. A smaller loan generally means lower interest costs and a more manageable repayment obligation.
Common Mistakes to Avoid When Using a Personal Loan
Even a useful financial product can become a burden when used irresponsibly. Here are some common mistakes borrowers should avoid:
- Borrowing without a repayment plan: Always determine how you will repay the loan before applying.
- Ignoring additional fees: Processing charges and other costs can significantly increase the total borrowing expense.
- Choosing the wrong lender: Compare lenders based on transparency, reputation, interest rates, and repayment conditions.
- Using loans for unnecessary purchases: Avoid accumulating debt for luxury items or impulse spending.
- Missing monthly payments: Late payments may result in additional charges and negatively affect your credit history, depending on local reporting practices.
- Taking multiple loans unnecessarily: Managing several loan obligations can increase financial stress.
Making informed borrowing decisions can help you avoid these problems and maintain better control over your finances.
Conclusion
A personal loan can be a valuable financial resource when used for the right reasons. Whether you are consolidating high-interest debt, managing medical expenses, improving your home, investing in education, or handling essential personal costs, responsible borrowing can provide useful financial flexibility.
However, the benefits of a personal loan depend on how carefully you manage the borrowed money. Always compare lenders, understand the total repayment cost, review the loan agreement, and choose monthly installments that fit your budget.
The smartest approach is to borrow with a clear purpose, spend carefully, and repay consistently. By following these seven smart strategies, you can make more informed financial decisions and use personal loans as a practical tool rather than an unnecessary financial burden.
Remember: A personal loan should support your financial goals, not create additional financial stress. Borrow responsibly and make every financial decision with your long-term stability in mind.
Frequently Asked Questions (FAQs)
1. What is the best way to use a personal loan?
The best way to use a personal loan is for essential and planned expenses, such as debt consolidation, necessary home repairs, medical costs, or professional development. The right choice depends on your financial situation and repayment ability.
2. Can I use a personal loan for anything?
Personal loans generally offer flexibility, but permitted uses depend on the lender’s policies and applicable regulations. Some lenders restrict certain uses, so always review the loan agreement.
3. Is using a personal loan to pay off credit card debt a good idea?
It can be beneficial if the personal loan has a lower overall borrowing cost and a manageable repayment schedule. Compare interest rates, fees, and total repayment amounts before making a decision.
4. Does taking a personal loan affect my credit score?
Applying for a personal loan may involve a credit inquiry, which can temporarily affect your credit score. Your repayment history, outstanding debt, and overall credit management can also influence your credit profile.
5. How much should I borrow through a personal loan?
You should borrow only the amount required for your specific purpose. Consider your monthly income, existing financial obligations, interest rate, and repayment capacity before deciding.
6. Can I repay a personal loan early?
Many lenders allow early repayment, but some may charge prepayment or early settlement fees. Check the loan agreement to understand the applicable conditions.
7. What should I compare before choosing a personal loan?
Compare the interest rate, annual percentage rate (APR), loan term, processing fees, monthly installment, total repayment amount, lender reputation, and repayment flexibility before selecting a loan.